The Healthcare Hegemony: How HSAs Turned Insurers into Banks
How healthcare companies are using health savings accounts (HSAs) to act as banks, capturing $146 billion in sticky deposits via embedded finance.
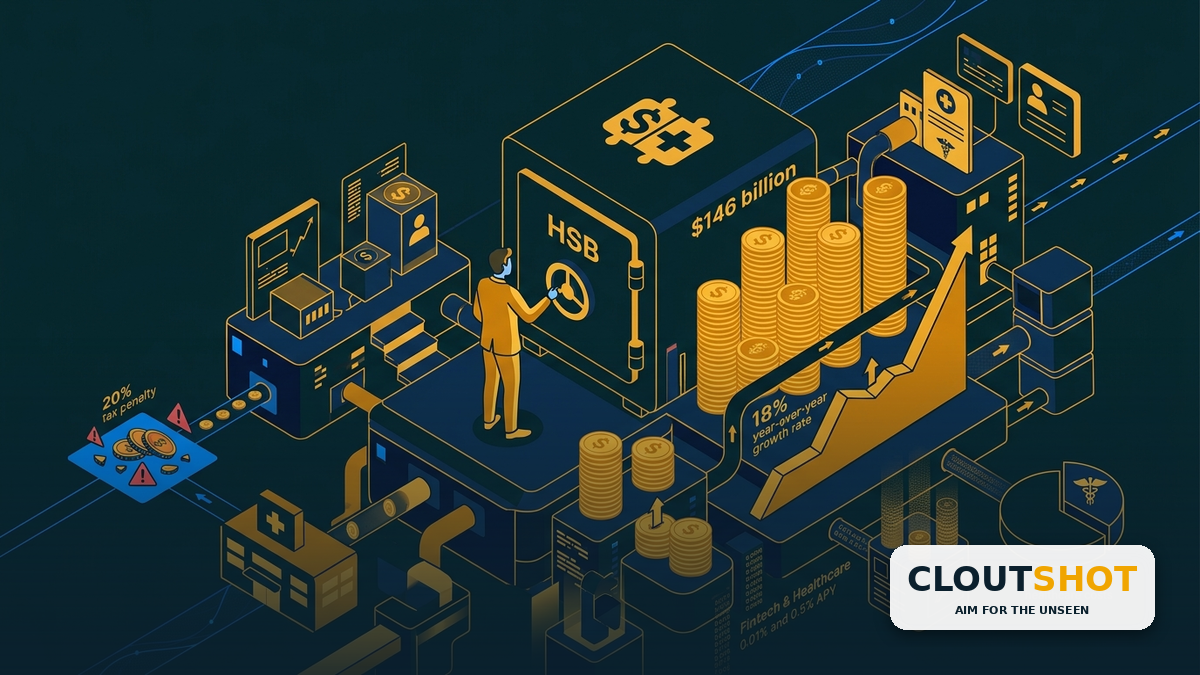
Health savings accounts (HSAs) have evolved into a major financial market, with assets hitting $146 billion. By using high federal funds rates and embedded banking software, healthcare providers and fintech platforms are transforming into deposit-gathering banks. This shift turns sticky, low-cost medical cash into a high-yield revenue engine while redesigning modern employee benefits.
The Rise of the Health-Wealth Deposit Engine
In 2024, total health savings account (HSA) assets in the United States surged to $146 billion, representing an 18% year-over-year growth rate according to the Morningstar 2025 HSA Landscape Report. The underlying driver of this surge is a fundamental structural shift: health insurance is no longer just a risk-mitigation tool. It is becoming a banking operation.
When consumers save money in an HSA, that cash does not sit in a vacuum. It must be held by a bank custodian. In a high interest rate environment where the federal funds rate remains elevated, these deposits have become a gold mine. Unlike traditional savings accounts, HSA balances are sticky. Because users face a 20% tax penalty on non-medical withdrawals before the age of 65, they keep their accounts funded during economic downturns.
For financial institutions and healthcare administrators, this means access to massive, low-cost deposit pools. According to data from the fintech infrastructure provider First Dollar, while banks pay retail savers nominal interest rates on HSA cash, often between 0.01% and 0.5% APY, they reinvest those same billions at the federal funds rate. This dynamic creates a massive net interest margin (NIM) and turns healthcare platforms into some of the most lucrative deposit-gatherers in the financial ecosystem.
Overcoming the Paper Chase: The Embedded Finance Solution
In the past, health benefits were a fragmented nightmare. As highlighted in a report by Fintech Wrap Up, providers deal with three distinct transaction flows: patient-to-provider copays, payer-to-provider insurance reimbursements, and provider-to-patient refunds. Most of this was handled via paper checks and slow ACH transfers, with a Harvard economics study noting that administrative work accounts for roughly one-third of all healthcare costs.
Now, API-first fintech platforms are rebuilding this stack from scratch. Companies like Lynx Finhealth, Benepass, and First Dollar have built infrastructure that embeds banking directly into healthcare software. By partnering with banking-as-a-service (BaaS) engines like Unit or Treasury Prime, these companies allow health plans to offer unified cards.
Instead of carrying separate plastic cards for HSAs, Flexible Spending Accounts (FSAs), Health Reimbursement Arrangements (HRAs), and wellness incentives, employees can now use a single card. On the backend, smart ledgering software scans, categorizes, and routes the transaction to the correct benefit account. This system reduces account costs by up to 90% for benefit administrators, according to case studies by Treasury Prime, and makes employee benefits far easier to use.
The Pushback Against Junk Fees and Low Interest Rates
This rapid transformation from healthcare to banking has not gone unnoticed by regulators. In May 2024, the Consumer Financial Protection Bureau (CFPB) released an Issue Spotlight exposing "junk fees and high costs" in the HSA market. The CFPB noted that many legacy custodians charge hidden fees, such as $25 account closure fees, $2.50 monthly maintenance fees, and $1.50 paper statement fees, while paying consumers almost no interest on cash balances.
This regulatory scrutiny is accelerating a wave of market disruption. Traditional giants like HSA Bank (a division of Santander Bank and Webster Bank) and HealthEquity are facing intense pressure from zero-fee, high-yield digital upstarts. Fidelity and Lively, for instance, have gained substantial market share by eliminating monthly maintenance fees, offering commission-free self-directed investment portfolios, and sweeping cash balances into higher-yield accounts.
With the passage of the One Big Beautiful Bill Act in July 2025, which Morningstar expects to expand the HSA market by three to four million participants, the competition for consumer deposits is fiercer than ever. The IRS also raised contribution limits for 2026 to $4,400 for individuals and $8,750 for families, further sweetening the pot.
Operator Playbook
Ditch the Multi-Card Stack:* Shift your company benefits to unified smart card providers. Carrying multiple plastic cards for different medical stipends is a friction point that leads to unused benefits. Audit Your HSA Custodian for Junk Fees:* Stop letting legacy administrators drain your employees' savings. Switch to platforms that charge zero maintenance fees and offer automated investment options with no minimum balance thresholds. Integrate Embedded Finance Early:* If you run a vertical SaaS platform or healthcare practice, embedding point-of-sale financing and automated billing can shorten your billing cycles and secure a share of the deposit float.
Frequently Asked Questions
How do healthcare companies act as banks? By offering health savings accounts, healthcare platforms act as custodians for cash deposits. They hold these deposits in bank partners to earn interest on the float, while providing consumers with debit cards, electronic ledgers, and credit options.
What makes HSA deposits attractive to financial institutions? HSA deposits are sticky because tax rules penalize users 20% for withdrawing money for non-medical reasons before age 65. This prevents consumers from panic-withdrawing their cash during recessions, providing banks with a stable source of low-cost funding.
What are the IRS HSA contribution limits for 2026? The contribution limit is $4,400 for self-only coverage and $8,750 for family coverage. Individuals aged 55 or older can contribute an additional $1,000 as a catch-up contribution.
Sources & References
Morningstar - "2025 Health Savings Account Landscape report detailing market size and provider assessments" First Dollar - "Analysis of bank interest in HSAs and net interest margins under high interest rates" CFPB - "May 2024 Issue Spotlight identifying junk fees and high costs in the HSA market" Treasury Prime - "Case study of embedded financial infrastructure and platform costs with Benepass and First Dollar" * American Bankers Association - "Data on employee contributions and legislative efforts to expand health savings accounts"